Dividend Investing in 2026: Yield vs. Growth Math, Dividend Safety, and Taxes
How dividend investing works in 2026: yield vs. growth math, payout safety checks, yield traps, qualified dividend and REIT tax rules, and account placement.
Dividend investing means building a portfolio around companies that pay cash to shareholders. It appeals for obvious reasons: the payments arrive whether markets are up or down, and companies with long records of raising dividends tend to be mature and profitable. It also has less obvious costs. Dividend portfolios often trail the broad market when growth stocks lead, and a dividend is not free money, since the share price falls by about the dividend on the ex-dividend date. Hartzmark and Solomon's 2019 Journal of Finance paper, "The Dividend Disconnect," found that many investors treat dividends as free income anyway.
The S&P 500 itself yields only about 1.05% in September 2026 (Multpl), near its lowest on record, because the largest technology companies pay little or nothing. An income-focused portfolio therefore looks quite different from the index. This guide covers the yield-versus-growth trade-off, how to check whether a dividend is safe, the 2026 tax rules, and where to hold dividend stocks.
Yield versus dividend growth
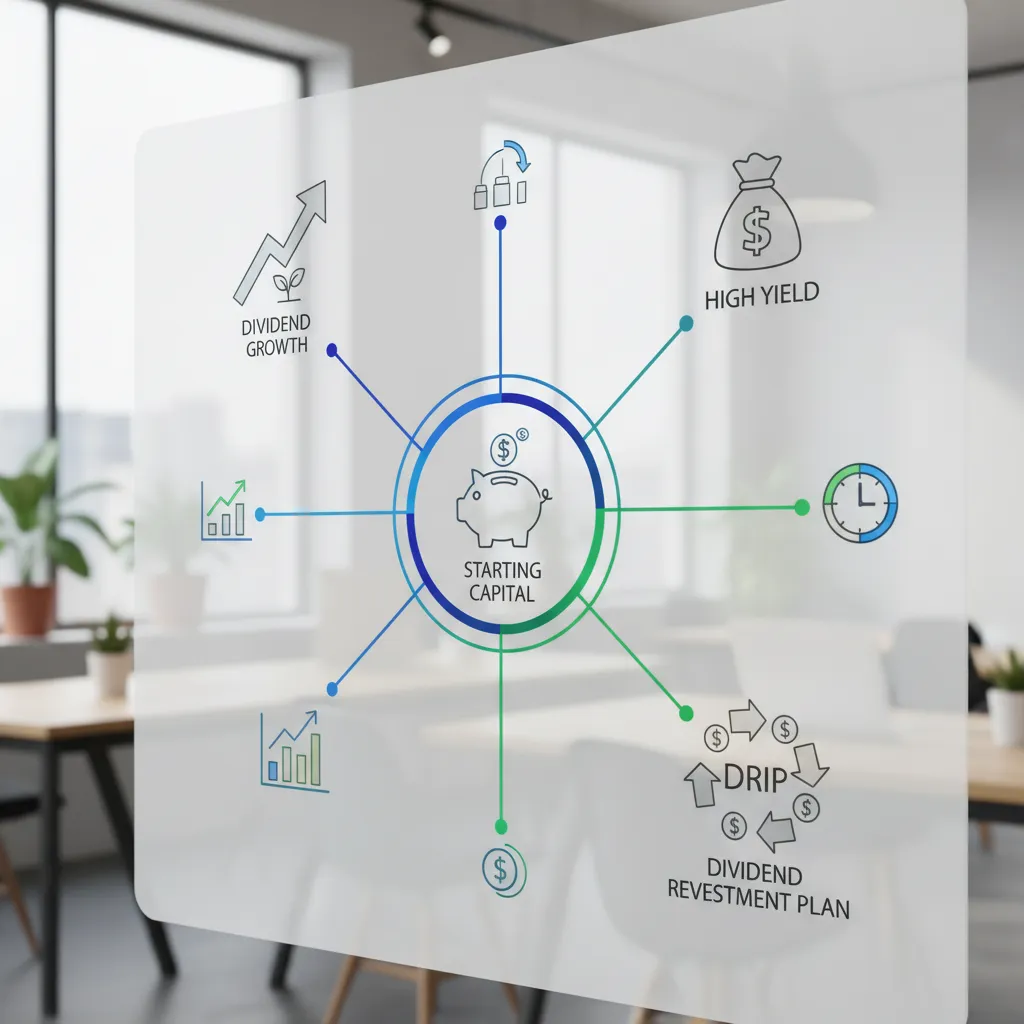
Income investors usually choose between two kinds of stock:
- High current yield, often 4% to 7%: utilities, REITs, tobacco, telecom, some energy and pipeline companies. More income now, slower growth.
- Dividend growth, often 1% to 2.5% yields with payouts rising 7% to 12% a year: companies with growing earnings and low payout ratios.
The claim that dividend growth always wins deserves a check.
An illustration: when does growth catch up?
Put $100,000 into each of two stocks, ignoring reinvestment and price changes:
- Stock A yields 5% ($5,000 a year) and raises the dividend 2% a year.
- Stock B yields 1.5% ($1,500 a year) and raises it 10% a year.
In year 10, A pays about $5,975 and B about $3,537. B's annual payment first passes A's in year 17. B's cumulative income does not catch up until year 27. Dividend growth wins over very long horizons, provided the 10% growth actually lasts, which few companies manage for decades. For someone who needs income within ten years, the higher yielder may be the better tool, if the dividend is safe.
Checking whether a dividend is safe
- Earnings payout ratio. Dividends divided by earnings. Under about 60% leaves room for a bad year in most industries; utilities often run higher on steady regulated earnings.
- Free cash flow payout. Dividends divided by operating cash flow minus capital spending. Dividends are paid in cash, so this matters more than accounting earnings.
- Debt. Rising interest costs compete with the dividend. Watch net debt to EBITDA and upcoming maturities.
- REITs and partnerships. REITs must pay out at least 90% of taxable income, so use funds from operations (FFO) or adjusted FFO instead of net income. See our REIT guide.
- History. A long record of increases shows management's priorities, but it is not a guarantee.
Yield traps
A very high yield is often a falling share price in disguise: the market expects a cut. When the cut comes, the investor loses the income and the price decline together. Even long records can end. Walgreens left the S&P 500 Dividend Aristocrats in January 2024 after cutting its dividend and later suspended it, 3M left in 2024 after cutting its dividend following the Solventum spin-off, and V.F. Corporation left in 2023 after a cut. A yield well above the company's own history and its peers, alongside a payout ratio over 100% or falling cash flow, is the warning sign.
Aristocrats, Kings, and dividend funds
The S&P 500 Dividend Aristocrats index holds S&P 500 members with at least 25 consecutive years of dividend increases that also meet size and trading requirements. It had 69 members in 2026; the January rebalance made no changes. Members leave when they fail to raise the dividend in a calendar year or leave the S&P 500. "Dividend Kings" is an informal list of companies with 50 or more years of increases.
Buying individual stocks gives control over yield, sectors, and taxes, but concentration is a risk; dividend payers cluster in utilities, consumer staples, financials, industrials, and real estate. Dividend ETFs spread that risk cheaply, and some screen for dividend growth, others for high yield. Check what a fund's screen does to sector weights before buying. For the broad-market alternative, see our index fund guide.
Dates that matter
- Declaration date: the board announces the dividend.
- Ex-dividend date: buy before this date to receive the dividend. Since US stock trades moved to one-day settlement on May 28, 2024 (SEC), the ex-dividend date is generally the same day as the record date.
- Payment date: cash arrives, or is reinvested if you use a dividend reinvestment plan (DRIP).
Buying just before the ex-date to "capture" a dividend does not work on its own: the price drops by about the dividend, and if you sell too soon the dividend is taxed as ordinary income instead of at the qualified rate.
Taxes in 2026
Qualified dividends are taxed at long-term capital gains rates, set for 2026 by IRS Revenue Procedure 2025-32:
| Rate | Single | Married filing jointly |
|---|---|---|
| 0% | Taxable income up to $49,450 | Up to $98,900 |
| 15% | Up to $545,500 | Up to $613,700 |
| 20% | Above $545,500 | Above $613,700 |
The 3.8% net investment income tax applies above modified adjusted gross income of $200,000 single or $250,000 joint. To be qualified, a dividend must come from a US company or a qualifying foreign one, and you must hold the stock more than 60 days during the 121-day period that begins 60 days before the ex-dividend date (IRS Publication 550).
Most REIT dividends are ordinary income, but 20% of qualified REIT dividends is deductible under Section 199A, which the One Big Beautiful Bill Act made permanent from 2026. That cuts the top federal rate on them from 37% to 29.6%.
An illustration: three households
- A retired married couple with $40,000 of qualified dividends and no other income has taxable income of $7,800 after the $32,200 standard deduction. Their federal tax on the dividends is $0.
- A single filer earning $120,000 in wages who receives $10,000 of qualified dividends pays 15%, or $1,500.
- The same filer with $10,000 of REIT dividends in the 24% bracket pays tax on $8,000 after the 199A deduction: $1,920, against $2,400 without it.
Where to hold dividend stocks
- Taxable accounts: broad US dividend stocks paying qualified dividends, especially for investors in the 0% or 15% bracket. Foreign dividend stocks also fit here, because tax withheld by other countries can usually be claimed as a foreign tax credit; inside an IRA that withholding is simply lost.
- Traditional IRA or 401(k): ordinary-income payers such as REITs, bond funds, and business development companies.
- Roth IRA: the holdings you expect to grow most, since growth and income there are never taxed.
Coordinate placement with your overall plan; our investment tax planning guide covers asset location in more detail.
Reinvest or take the cash?
Reinvesting through a DRIP buys more shares automatically, often in fractional amounts and without commissions. Reinvested dividends in a taxable account are still taxed in the year paid, and each purchase creates a new tax lot, so keep the records your broker provides. A DRIP in one account can also trigger a wash sale if you sold the same stock at a loss in another account within 30 days; see our tax-loss harvesting guide.
In retirement, many investors switch dividends to cash and spend them. That works if you plan withdrawals on total return: selling some shares is not worse than receiving a dividend of the same size, and it can be taxed less.
Setting an income target
An illustration: $40,000 of annual income requires about $1.14 million at a 3.5% portfolio yield, and about $3.8 million at the S&P 500's roughly 1.05% yield. A total-return approach that withdraws 4% a year from a diversified portfolio would need $1 million, with the income coming partly from dividends and partly from selling shares. Chasing a higher yield to shrink the capital needed usually means taking more risk of cuts. For withdrawal planning, see our retirement income guide.
Getting started
- Set an income target and decide whether you will live on dividends alone or on total return.
- Choose between a dividend ETF and individual stocks; with individual stocks, hold enough names and sectors that one cut does not matter much.
- Screen for payout ratios, free cash flow coverage, and debt, not just yield.
- Place holdings by tax treatment: qualified payers in taxable accounts, ordinary-income payers in IRAs.
- Decide whether to reinvest, and watch for wash sales across accounts.
- Rebalance at least yearly so no sector dominates; our rebalancing guide covers methods.
This guide is for informational purposes only and does not constitute investment or tax advice. Figures are as of September 2026. Dividends can be cut or suspended, and dividend stocks can lose value. Consult a qualified CPA and a fiduciary financial advisor about your situation.
Frequently Asked Questions
Share this article
Related Articles
How to Invest in REITs in 2026: Returns, Sectors, FFO and AFFO, Taxes, and Non-Traded REIT Risks
REIT investing with 2026 data: sector returns and yields, FFO vs. AFFO with a worked example, how REIT dividends are taxed after OBBBA, and non-traded REITs.
Preferred Stock Investing: Income & Stability
How preferred stock behaves in practice: rate and call math, where holders rank when a bank fails, which dividends get lower tax rates, and fund costs.
Investment Tax Planning for 2026: How Income Stacks, Roth Conversions, IRMAA, and the Hidden Rates Between Brackets
2026 investment tax planning: how dividends stack on other income, a Roth conversion example with hidden 27% to 30% rates, IRMAA and NIIT, and a calendar.
Tail Risk Hedging: What Put Protection Costs, When It Pays, and How Collars and Put Spreads Change the Trade
Rolling 10% out-of-the-money S&P 500 puts costs about 2.3% to 2.6% a year at 20% implied volatility. Cost math, collars, put spreads, and Cboe index data.