Invoice Factoring in 2026: True Cost, Recourse Terms, Accounting, Government Invoices, and Lessons From First Brands
How invoice factoring works in 2026: its cost as an annual rate, recourse vs. non-recourse, accounting and legal rules, and lessons from First Brands.
Invoice factoring turns unpaid business invoices into cash in a day or two. A company that sells on 30, 60, or 90-day terms sells those invoices to a factor, gets most of the money up front, and receives the rest, minus a fee, when its customer pays. Because the factor is relying on your customers' credit, factoring is available to young or thinly capitalized businesses that a bank would turn down.
It is also one of the more expensive forms of business finance once the fees are expressed as an annual rate, and the legal and accounting details are different from a loan. This guide covers how a factoring agreement works, what it costs, recourse terms, how it shows up on your financial statements, the special rules for government invoices and state disclosure laws, and what the 2025 collapse of auto parts supplier First Brands changed.
How a factoring agreement works
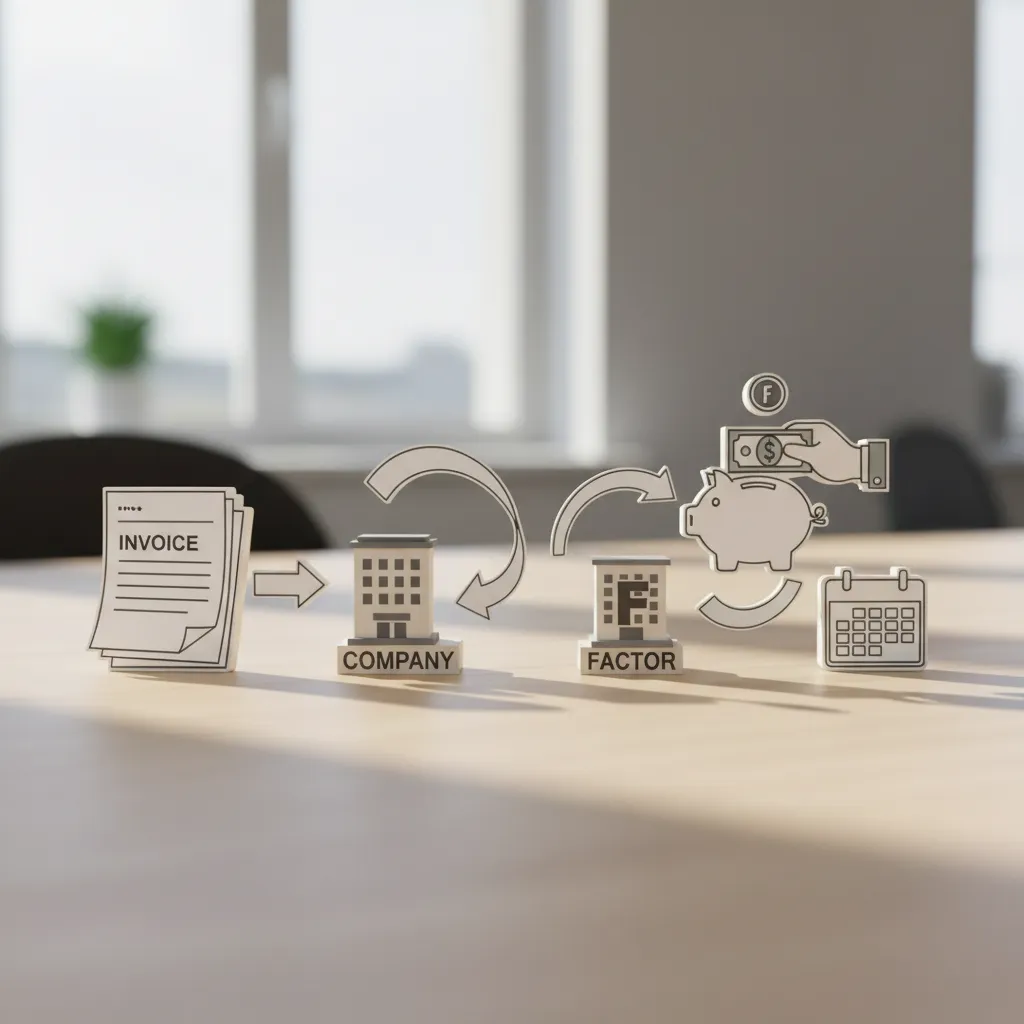
- You deliver goods or services and invoice your business or government customer.
- You submit the invoice to the factor, which checks your customer's credit and often confirms the invoice directly with the customer.
- The factor advances a percentage of the invoice, commonly 70% to 90%, and holds the rest as a reserve.
- Your customer pays the factor, usually into a lockbox account in the factor's control.
- The factor releases the reserve minus its fees.
Before funding, the factor will file a UCC-1 financing statement covering your receivables. If your bank already has a lien on all your assets, the bank must agree to release or subordinate its claim on the factored invoices, and many bank loan agreements forbid factoring without consent. Read your existing loan documents first.
Some invoices are hard or impossible to factor: invoices for work not yet performed, including subscriptions billed in advance; progress billings and construction retainage; invoices to customers that can offset amounts you owe them; and consumer receivables. Factoring fits businesses that deliver first and bill creditworthy business or government customers afterward, such as staffing firms, trucking companies, manufacturers, distributors, and government contractors.
What it costs
Factors quote fees as a percentage of the invoice for a period. A common structure is a flat fee for the first 30 days plus an added fee for each later period. Other charges can include application or setup fees, wire and ACH fees, credit check fees, monthly minimum volume fees, and termination fees in long contracts.
An illustration with a $100,000 invoice, an 85% advance ($85,000), and a fee of 2% for the first 30 days plus 1% for each additional 15 days:
| Customer pays on day | Factoring fee | Reserve returned to you | Annualized cost on the $85,000 advanced |
|---|---|---|---|
| 20 | $2,000 | $13,000 | 42.9% |
| 30 | $2,000 | $13,000 | 28.6% |
| 45 | $3,000 | $12,000 | 28.6% |
| 90 | $6,000 | $9,000 | 28.6% |
For comparison, the bank prime rate was 7.00% in September 2026 after the Federal Reserve's September 17 increase. A bank line of credit at prime plus 2% would cost about $943 to borrow $85,000 for 45 days, against $3,000 in the table. Offering your customers a 2% discount to pay in 10 days instead of 30 costs about 37% a year, so it is no bargain either, but it keeps the factor out of the relationship.
Factoring can still make sense when the alternative is turning down an order, missing payroll, or a merchant cash advance. It makes less sense as permanent financing for a business with thin margins. If your gross margin is 20% and factoring costs 3% of revenue, it takes 15% of your gross profit. Our guides to small business loans, revenue-based financing, and building business credit cover the cheaper options you can work toward.
Recourse and non-recourse
With recourse factoring, you must buy back or replace any invoice that is not paid within a set period, often 90 days. You keep the credit risk, and the fee is lower.
With non-recourse factoring, the factor absorbs the loss if your customer cannot pay because of insolvency. Read the definition closely. Non-recourse almost never covers commercial disputes, so if your customer refuses to pay because of late delivery or a quality complaint, the invoice comes back to you. Some agreements limit non-recourse protection to customers the factor has pre-approved, or to a credit limit per customer.
Other terms to compare between offers:
- Spot factoring (selected invoices) versus whole-ledger factoring (all receivables), which usually costs less per invoice but ties up your entire ledger.
- Minimum monthly volume and the fee if you fall short.
- Contract length, automatic renewal, and termination fees.
- How the reserve is released, per invoice or in a monthly settlement.
- What happens to invoices that pass the recourse period.
How factoring shows up on your financial statements
Factoring is often sold as "not a loan," and legally it may be a sale. Accounting is a separate question. Under US GAAP, ASC 860 treats a transfer of receivables as a sale only if three conditions are met: the receivables are legally isolated from your company even in bankruptcy, the factor is free to pledge or sell them, and you keep no effective control over them. Heavy recourse makes legal isolation harder to show. If the transfer fails these tests, the receivables stay on your balance sheet and the cash you received is recorded as a liability.
That matters if you have loan covenants, if you are raising equity, or if you plan to sell the business. Buyers and lenders will ask how much of your working capital comes from factoring, and describing a secured borrowing as off-balance-sheet can create problems in due diligence. Talk to your accountant before signing.
Notification, verification, and your customers
In most factoring, your customers are told to pay the factor. Under UCC 9-406, once a customer receives that notice, it can discharge the debt only by paying the factor, so paying you by mistake does not settle the invoice. The same section generally makes contract terms that prohibit assigning the receivable ineffective.
Factors also verify invoices, often by contacting your customer's accounts payable team before funding. Ask how they do it, how often, and what their collections staff say when an invoice is late. Non-notification factoring, where customers keep paying you, exists but is usually limited to larger businesses with strong records.
Government invoices
Payments under federal contracts are covered by the Assignment of Claims Act. An assignment is generally allowed only to a bank, trust company, or other financing institution, and it must be filed with the contracting officer and the disbursing office following FAR subpart 32.8. Until that happens, the government can keep paying you and has no obligation to the factor. Factors that specialize in government receivables handle the filings; generalist factors may decline.
State disclosure laws
As of March 2026, ten states required some form of cost disclosure for commercial financing: California, Connecticut, Florida, Georgia, Kansas, Missouri, New York, Texas, Utah, and Virginia. The broader laws, including California's (offers of $500,000 or less) and New York's (up to $2.5 million), cover factoring and require a disclosure of the estimated annual percentage rate. Connecticut, Texas, and Virginia cover only sales-based financing such as merchant cash advances. If you are in a covered state, you should receive a disclosure before signing; use it to compare offers.
What First Brands changed
First Brands Group, an auto parts supplier, filed for bankruptcy in September 2025 owing about $2.3 billion to receivables financiers under factoring and supply chain finance programs, on top of its reported debt. A court-appointed examiner reported in April 2026 that the company obtained financing by submitting falsified invoice data, and that in the North American programs lenders typically relied on manually prepared spreadsheets without checking the underlying invoices. The founder and his brother were indicted in January 2026 and have pleaded not guilty. One of the financiers, Raistone, filed for Chapter 7 liquidation in February 2026.
For an ordinary business that factors honestly, the practical effects are more verification of invoices, more requests for direct access to accounting data, and more questions from lenders, auditors, and buyers about how much of your working capital comes from receivables finance. Expect them and keep clean records: invoices that match shipments or timesheets, and an aging report that reconciles to your books.
Before you sign
- Pull your receivables aging report and list which customers and invoices a factor would accept.
- Get written offers from at least three factors, and convert each to an annual cost using your customers' actual payment times.
- Read the recourse definition, dispute exclusions, minimum volume, term, and termination clauses.
- Get your bank's consent or subordination if it has a lien on your receivables.
- Ask your accountant how the arrangement will be recorded.
- Tell your largest customers before the first notice arrives, so the change in payment instructions does not surprise their accounts payable team.
- Set a plan to move to cheaper financing, such as a bank line of credit, as your record and margins improve. Our working capital guide and cash flow management guide cover shortening the cash cycle so you need less financing.
This guide is for informational purposes only and does not constitute legal, accounting, or financial advice. Factoring terms vary widely by provider, industry, and customer credit. Rates and laws are as of September 2026, and the cost table is an illustration. Consult an accountant and attorney before signing a factoring agreement.
Frequently Asked Questions
Share this article
Related Articles
Working Capital and Growth: Cash Conversion Cycle Math, Supplier Terms, and Real Company Figures
How growth consumes working capital: DSO, DIO, and DPO worked through, early-payment discounts, supplier finance disclosure, and HP, Nike, and Walmart figures.
Cash Flow Management for Growing Businesses: Forecasts, Working Capital, and Safety
Build a 13-week cash forecast, measure the cash conversion cycle, work out how much cash growth consumes, and protect balances above FDIC limits. With examples.
AI in Supply Chain Finance: Discount Math, Disclosure Rules, and Lessons From First Brands
How reverse factoring and dynamic discounting work, the annualized cost of early-payment discounts, new disclosures, and where AI catches invoice fraud.
Private Equity Value Creation: Strategic Portfolio Growth
Where private equity returns come from now: the math of a value creation bridge, why deals need 10-12% EBITDA growth, and which operating levers work.