Mezzanine Financing in 2026: What It Costs, How PIK and Warrants Work, and When It Beats Selling Equity
How mezzanine debt works for mid-sized companies: where it sits, its real cost with PIK and warrants, a worked comparison with selling equity, and key terms.
Mezzanine financing fills the gap between what a senior lender will lend and what the owners can or want to put in. A company buying a competitor for $10 million might get most of the price from its bank, but the bank stops at a multiple of earnings it considers safe. The remainder can come from selling shares or from mezzanine debt: a loan that ranks behind the bank, charges more, and usually takes a small slice of the upside through warrants.
It is expensive capital, and whether it is cheaper than equity depends on how fast the business grows. This guide covers where mezzanine sits, what it costs once PIK interest, fees, and warrants are counted, a worked comparison with selling a minority stake, the terms that cause trouble, and where to find it.
Where mezzanine sits
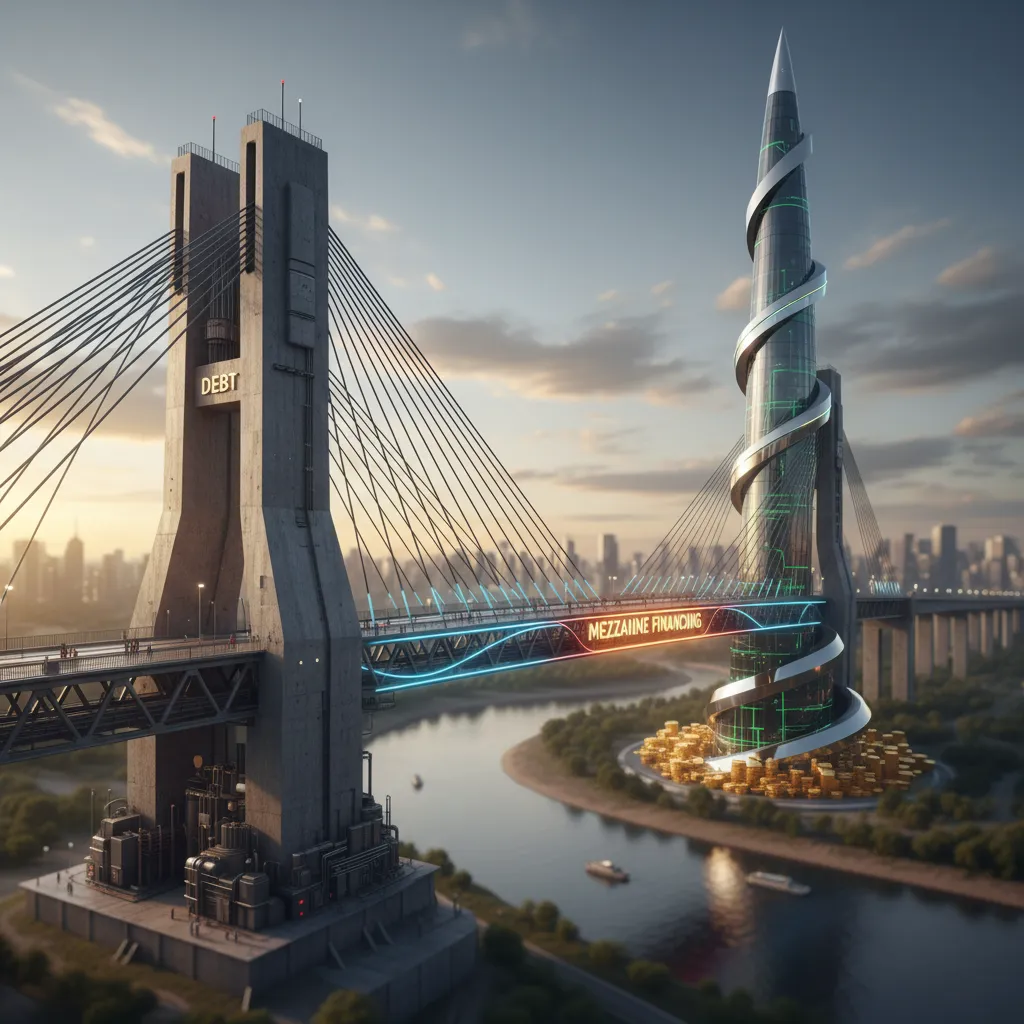
| Layer | Security and priority | Typical features |
|---|---|---|
| Senior secured loan | First claim on assets; paid first | Floating rate over SOFR, amortization, tighter covenants |
| Unitranche loan | One loan combining senior and junior debt, first lien | Single blended rate from a private credit fund; often replaces senior plus mezzanine |
| Second-lien loan | Second claim on the same collateral | Higher spread, fewer covenants |
| Mezzanine debt | Usually unsecured or second-lien, contractually subordinated | Cash and PIK interest, warrants, five- to seven-year bullet maturity |
| Preferred equity | Ranks ahead of common shares, no fixed repayment | Accruing dividend, redemption rights |
| Common equity | Last claim; keeps all remaining upside | No fixed cost |
Mezzanine usually adds about one turn of EBITDA on top of senior debt. Prairie Capital Advisors' Winter 2026 middle-market review put mezzanine at 0.8 times EBITDA in typical deal structures in the second quarter of 2025, up from 0.6 times in 2024 and above the 0.7 times average for 2018 to 2023. Private credit funds have taken much of the market with unitranche loans, which give one lender the whole debt package at a blended rate, but mezzanine remains common in lower middle-market buyouts and in deals where the senior lender will not stretch further.
What it costs
A mezzanine term sheet has several price components, and comparing only the headline coupon is a common mistake:
- Cash interest, usually fixed, paid quarterly.
- PIK interest, added to the principal and repaid at maturity. It compounds, because later cash interest is charged on the larger balance.
- An upfront fee, typically deducted from the amount funded.
- Warrants for a small percentage of the fully diluted equity, often at a nominal exercise price.
- Prepayment premiums (call protection) that make early refinancing expensive for the first few years.
An illustration: $10 million of mezzanine at 12% cash interest and 2% PIK, a 2% upfront fee, and a five-year bullet maturity. The principal grows to about $11.04 million by year five, cash interest totals about $6.24 million over the five years, and the lender's annual return is about 14.6% before warrants. Warrants for 2% of the equity raise it to roughly 15% to 18%, depending on what the company is worth at exit.
For SBA-licensed Small Business Investment Companies, the regulations set a ceiling. Under 13 CFR 107.855, the cost of money on a debt security (debt with equity features such as warrants) can be at least 14%, and on a straight loan at least 19%, with higher ceilings allowed when the SBIC's own borrowing costs rise; permitted closing fees are excluded. The example's 12% cash plus 2% PIK equals the 14% minimum ceiling for debt securities.
Mezzanine or equity: a worked comparison
The real alternative to mezzanine is often selling part of the company. An illustration, with simplified assumptions:
- A company worth $70 million with $20 million of senior debt, so $50 million of equity, all owned by the founder. It needs $10 million to buy a smaller competitor.
- Option A: $10 million of mezzanine on the terms above, with warrants for 2% of the equity. Cash interest is tax-deductible at 25%, so it costs about $4.68 million after tax over five years.
- Option B: sell a 16.7% stake to an equity investor for $10 million, valuing the equity at $60 million after the investment.
- After five years the company is sold, and the owner's proceeds are compared.
| Outcome after five years | Company value, senior debt | Owner's proceeds with mezzanine | Owner's proceeds with equity sale | Better choice |
|---|---|---|---|---|
| Strong growth | $140M, $10M | $111.8M | $108.3M | Mezzanine by $3.5M |
| Moderate growth | $98M, $10M | $70.6M | $73.3M | Equity by $2.7M |
| Stall | $60M, $15M | $28.5M | $37.5M | Equity by $9.0M |
In this example, mezzanine wins only if equity value grows faster than about 12% a year, which is below the lender's pre-tax return because the interest is deductible. With moderate growth, the equity investor's 16.7% costs less than the mezzanine. If the business stalls, the mezzanine still has to be repaid in full with its accrued PIK, while the equity investor simply shares the smaller outcome. And if earnings fall far enough that the company cannot refinance, the mezzanine lender, unlike a minority shareholder, can eventually enforce its claim.
The comparison leaves out things that also matter: the control and governance rights an equity investor would want, the covenants a lender would impose, and the owner's appetite for risk. Our guides to business valuation methods and leveraged buyouts cover how debt changes equity returns in more detail.
PIK interest: useful, but it compounds
PIK lets a company conserve cash while an acquisition is integrated or a growth project ramps up. The cost is that the debt grows. A $10 million loan accruing 14% entirely as PIK grows to about $19.25 million in five years, and the company then needs to refinance or sell to repay it.
Lenders watch PIK closely because it can hide stress. According to SOLVE data cited in the LSTA's first-quarter 2026 BDC review, PIK was included in 4.33% of new investments by business development companies in the first quarter of 2026, down from 9.47% a year earlier, while the weighted average non-accrual rate rose to 1.99% from 1.42% in the prior quarter. The LSTA suggested lenders may be reserving PIK for amendments to existing loans, which is how PIK often shows up when a borrower cannot pay cash interest.
For tax purposes, PIK interest and the value allocated to warrants generally create original issue discount, which the borrower deducts as it accrues rather than when paid. For debt with a maturity over five years, significant original issue discount, and a yield at least five percentage points above the applicable federal rate, the high-yield discount obligation rules can defer or disallow part of those deductions, and the business interest limit under Section 163(j) applies to the total. Tax counsel should model both before signing.
Terms that matter more than the rate
- The intercreditor or subordination agreement with the senior lender. It usually lets the senior lender block mezzanine payments for a period after a default and bars the mezzanine lender from enforcing its claim during a standstill period. Read how long each lasts and what triggers them.
- Covenants. Mezzanine covenants are normally set looser than the senior lender's, so the senior lender is the first to act. Make sure the cushion is real under a downside forecast.
- Warrant put rights. In private companies, warrants often come with the right to require the company to buy them back for cash at fair value at maturity, on a refinancing, or on a sale. Negotiate how fair value is set (an agreed formula or an independent appraiser) and when the put can be exercised, because it can require a large cash payment at the moment the company is refinancing.
- Call protection. Prepayment premiums make it expensive to refinance early if the company grows quickly or rates fall.
- Governance. Board observer rights, information rights, and consent rights over new debt, acquisitions, and dividends are common. Some lenders also ask for personal guarantees in small deals; resist them where possible.
- Change of control. A sale usually triggers repayment and the warrant put, which affects what the owner nets from a sale.
Where to find it
- Small Business Investment Companies are privately managed funds licensed by the SBA that borrow with SBA-guaranteed debentures and invest in smaller U.S. companies. The SBA reported that the program reached a record $53 billion of combined private capital and SBA leverage in fiscal year 2025 and licensed 48 new SBICs. Many will finance owner-run companies without a private equity sponsor.
- Mezzanine and private credit funds, including business development companies, lend mostly to companies owned by private equity firms. Our private credit guide covers them from the investor's side.
- Insurance companies buy subordinated notes in larger middle-market deals.
- Sellers often provide subordinated financing in small acquisitions through seller notes, at lower rates and without warrants.
Other options worth comparing before choosing mezzanine include SBA 7(a) loans (up to $5 million) for smaller acquisitions, covered in our small business loans guide; revenue-based financing for companies with recurring revenue but thin profits; and venture debt for venture-backed startups. Our guide to business debt compares the main forms of borrowing.
Before signing a mezzanine term sheet
- Calculate the all-in cost, including PIK, fees, prepayment premiums, and a range of warrant values, as an annual rate.
- Run the owner's proceeds under strong, moderate, and flat scenarios against the alternative of selling equity.
- Stress-test cash interest coverage and the ability to refinance at maturity if earnings fall 20% to 30%.
- Read the intercreditor agreement for payment blockage and standstill periods.
- Negotiate the warrant percentage, the put right, and how fair value is determined.
- Check how the structure interacts with Section 163(j) and the original issue discount rules.
- Compare at least two or three lenders, including an SBIC if the company qualifies.
This guide is for informational purposes only and does not constitute financial, tax, or legal advice. Mezzanine debt is high-cost, subordinated borrowing, and failure to repay can lead to loss of control of the business. The pricing and scenario figures are illustrations with simplified assumptions; market data are as of September 2026. Consult qualified financial, tax, and legal advisers before raising capital.
Frequently Asked Questions
Share this article
Related Articles
Private Debt: Strategic Business Funding
A borrower guide to direct lending: who qualifies, 2026 pricing, how much debt a company can carry, covenants, call protection, and what happens in trouble.
AI in M&A Due Diligence: Contract Review, QA Sampling, and Clean-Team Risks
Where AI speeds up due diligence, how to measure what it misses with a simple sampling test, and the confidentiality and clean-team rules deal teams must keep.
Capital Allocation: NPV vs IRR, Hurdle Rates, and Choosing Between Reinvesting, M&A, Debt Paydown, Dividends, and Buybacks
How to rank projects when NPV and IRR disagree, set a hurdle rate at a 5.24% Treasury yield, and weigh reinvesting, M&A, debt paydown, dividends, and buybacks.
Leveraged Buyouts in 2026: How the Math Works, Where Returns Come From, and What Breaks Them
How leveraged buyouts work in 2026: capital structure, a worked LBO with return attribution and stress tests, the interest deduction limit, and why deals fail.